Your retirement plan provider sends an amendment package with a December 31 deadline. You forward it for signature and move on. However, would your payroll records tell the same story as the document you’re about to sign?
The payroll settings and employee eligibility records behind that document may already need to reflect rules that took effect months earlier. For a business owner, that gap can turn routine paperwork into a costly correction.
SECURE 2.0 has reached the stage where implementation needs a closer look. Your plan document, payroll system, employee records, and tax return each capture a different part of the arrangement. If those pieces disagree, you could miss an employee’s enrollment date, misdirect a catch-up contribution, or budget for a credit your business can’t claim. A review before year-end should follow the money and the records through the entire process.
Amendment Deadlines and Operating Dates
For most private-sector qualified retirement plans that aren’t collectively bargained, the general deadline for amendments reflecting SECURE 2.0 and certain related laws is December 31, 2026. However, the plan must have been operating in accordance with the applicable provisions from their effective dates. A December signature won’t turn back the clock on an earlier operational failure.1
There’s also a separate deadline that can cause confusion. Certain amendments for IRAs, SEP arrangements, and SIMPLE IRA plans have been extended to December 31, 2027. That extension applies to those arrangements; it doesn’t give an ordinary small-business 401(k) another year.2
Ask your third-party administrator, or TPA, to identify which changes are mandatory, which optional features your business adopted, and when each became effective. Then compare those dates with actual payroll and enrollment records. An amendment describing a feature is only part of the evidence. You also need to know whether contributions and employee access followed the terms that were supposed to apply.
The Wage Test Behind Roth Catch-Ups
For 2026, a catch-up-eligible 401(k) participant whose 2025 wages from the sponsoring employer exceeded $150,000 generally must make catch-up contributions as Roth contributions. The test uses wages subject to Social Security taxes under the Federal Insurance Contributions Act, commonly called FICA wages. Household income, investment gains, and business distributions aren’t interchangeable with that figure.3, 4
This distinction can change an owner’s treatment. A partner with only self-employment income and no prior-year FICA wages from the sponsoring employer generally isn’t subject to the statutory Roth catch-up mandate. Someone who moved from employee to partner may have prior-year wages that trigger it. Have the administrator review the compensation history and plan terms before assuming that all highly paid owners belong in the same category.4
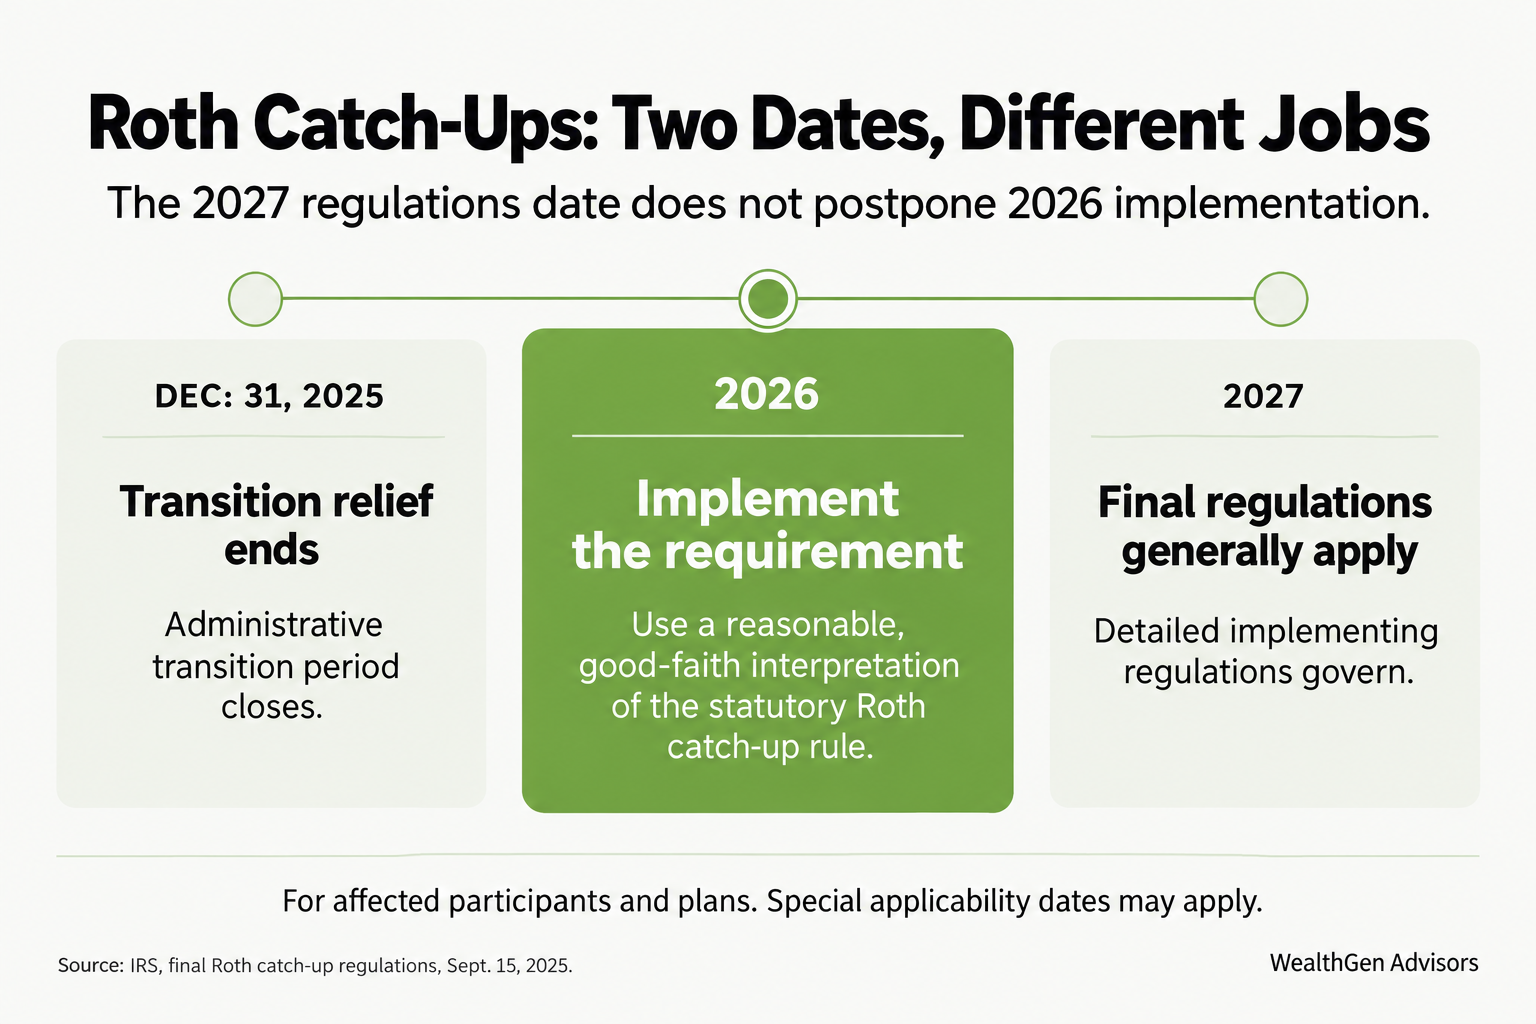
Another date can mislead employers: the final Roth catch-up regulations generally apply beginning in 2027, but the administrative transition period ended after 2025. Plans must implement the statutory requirement in 2026 using a reasonable, good-faith interpretation; the regulations’ later applicability date isn’t another blanket postponement.5
Once the affected participants are identified, trace a contribution from the paycheck to the recordkeeper. Confirm that payroll uses the right prior-year wage information and sends catch-up dollars to the Roth account when required. For the owner’s personal planning, those contributions also need to appear correctly in the current-year tax projection. A savings target built around a pretax deduction can leave less spending cash than expected when the contribution is made after tax.
A useful check is to request a sample payroll calculation and the corresponding contribution report. Compare the participant, contribution type, amount withheld, and amount received. If the two systems use different labels for catch-up contributions, have the providers explain how the information transfers. An enabled Roth feature on a provider’s website doesn’t establish that your payroll file is using it correctly.
Automatic Enrollment and Business Growth
Your business can outgrow a retirement-plan exemption before anyone thinks to revisit it. A small-business label alone doesn’t settle whether automatic enrollment is required. For plan years beginning after 2024, the requirement generally applies to 401(k) arrangements established on or after December 29, 2022. Exceptions include qualifying businesses that normally employ no more than 10 employees and businesses in existence for less than three years, including predecessor history. Older arrangements generally have a separate exemption.6
For covered plans, the initial default contribution rate must generally be between 3% and 10%, with annual increases of one percentage point until reaching at least 10%, subject to a 15% ceiling. Employees retain the ability to opt out or elect a different rate.6 Payroll therefore needs instructions for both initial enrollment and later increases.
If your business relied on a small-employer exception, put employee-count changes into the annual review. Hiring beyond the threshold can start the timetable for losing the exception; the precise application date needs to be confirmed. A Sarasota business adding another office should bring that expansion to the administrator before assuming its original exemption continues.
Automatic enrollment also doesn’t, by itself, create safe harbor protection from nondiscrimination testing. A qualifying safe harbor design has additional conditions, including employer contribution requirements.7 Ask which tests your plan must still pass and how higher employee participation could affect matching costs. That connects the administrative change to the business’s funding budget.
Part-Time Employees Missing From the Census
An employee can remain part-time on your staffing chart and become eligible to defer pay into the 401(k). For plan years beginning after 2024, the long-term, part-time rule generally requires access after two consecutive 12-month periods with at least 500 hours in each, provided the employee reaches age 21 by the end of the qualifying period. The ordinary one-year, 1,000-hour eligibility route remains relevant.8
Who’s missing from your eligibility report simply because they’ve always been labeled part-time? Consider a hypothetical employee, age 35, who records 600 hours in each of two applicable consecutive service periods. An eligibility report that checks only for 1,000 hours in a single year could miss that worker. Ask the administrator to determine the required entry date from the full service history and the plan’s terms.
For a business with recurring seasonal staff, that means retaining hours across seasons and reconciling rehire records. Earlier service can fall through the cracks during a payroll conversion if the new system starts with current-year totals and leaves prior hours in an old file. Send the administrator the complete census, including employees who aren’t currently contributing.
Eligibility for salary deferrals also needs to be distinguished from eligibility for employer contributions. Special rules can permit exclusion from matching or nonelective contributions for employees qualifying solely under the long-term, part-time provisions.8 Confirm the plan’s treatment before promising a match or excluding someone from all participation. The label in the payroll system won’t resolve that distinction.
The Credit Behind the Sales Estimate
Proposals for a new small-business plan often lead with a tax credit for startup costs. Under the rules for eligible employers, a credit for qualified startup costs of a new plan can be claimed for up to three years, and the figure quoted in sales material is generally the statutory maximum of $5,000 per year rather than an amount calculated for your business.
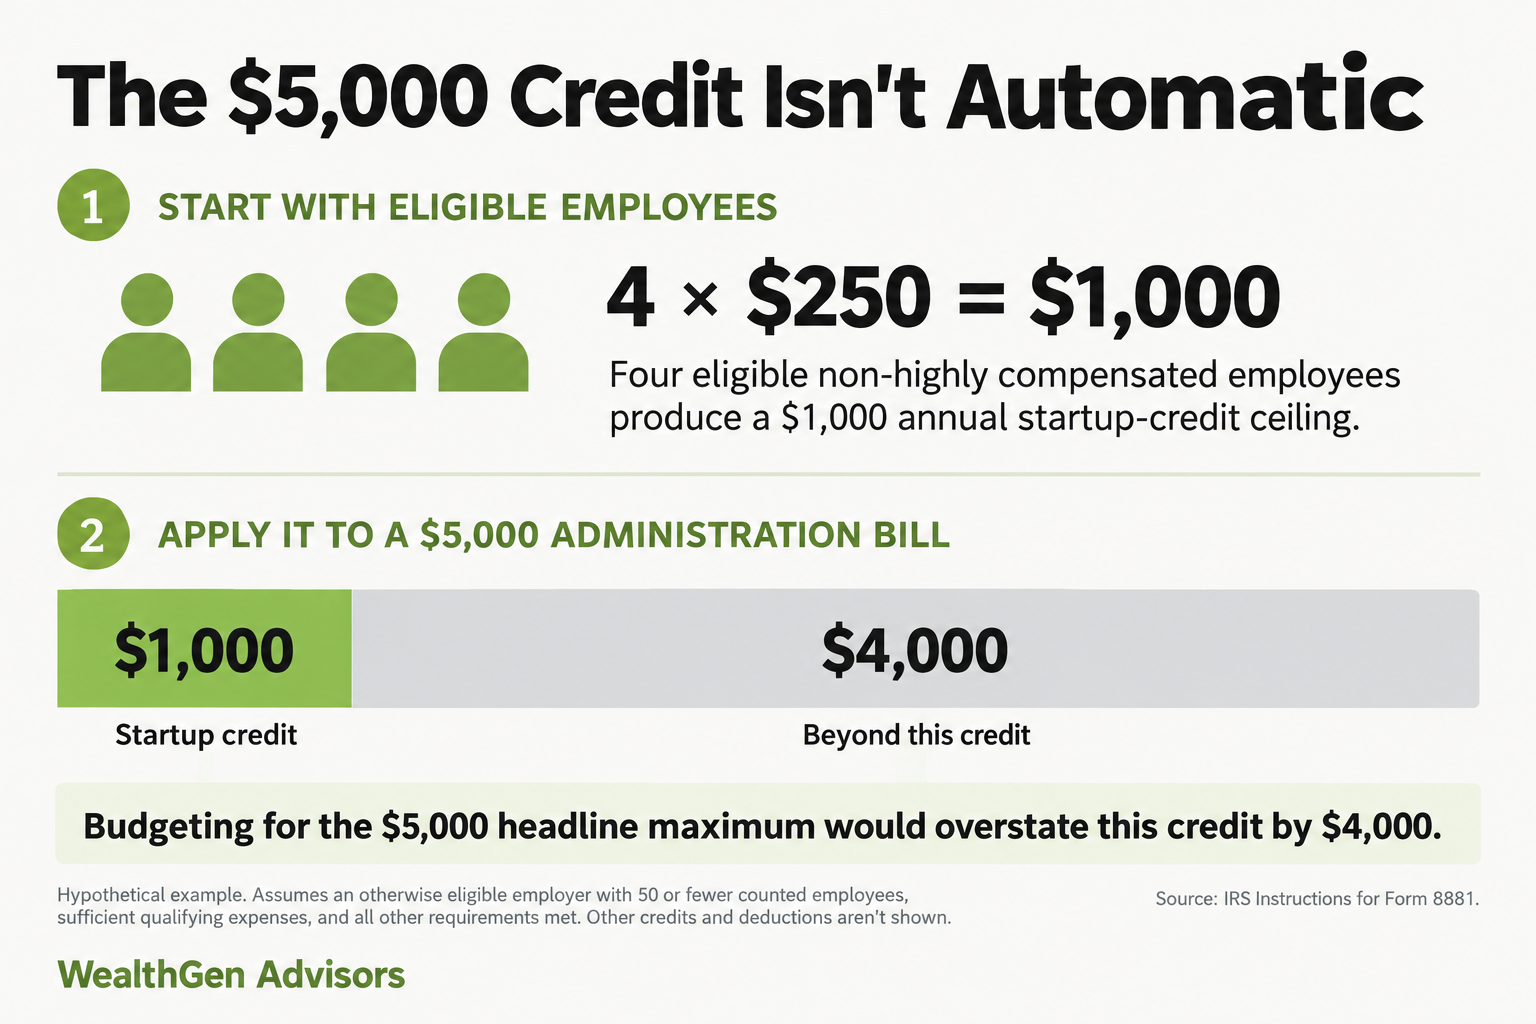
How much of that advertised $5,000 credit would your business qualify for? The words “up to” can carry a lot of weight in a retirement-plan proposal. Run the calculation using your own workforce. For an otherwise eligible employer with 50 or fewer counted employees, the startup credit can cover 100% of qualifying costs, subject to a separate ceiling. That ceiling is the greater of $500 or the lesser of $5,000 and $250 multiplied by the number of eligible employees who aren’t highly compensated.9
For example, four eligible non-highly compensated employees produce a $1,000 annual ceiling. Assuming all other requirements are met and qualifying expenses are sufficient, a $5,000 administration bill would therefore leave $4,000 beyond this particular credit. The headline maximum would overstate the benefit by $4,000.
Prior plan history can also prevent eligibility. Generally, you can’t claim the startup credit if your business maintained a qualified employer plan covering substantially the same employees during the relevant preceding three-year period. Moving providers doesn’t automatically create a fresh credit.9 Give your accountant the previous plan records before relying on the proposal’s estimate.
A separate employer-contribution credit may also be available, but it has its own employee, compensation, contribution, and phase-down rules. Startup costs used for the startup credit can’t also be deducted as the same expenses.10 Ask for a year-by-year after-tax cost estimate that separates these benefits from ongoing expenses. The plan still needs to pencil out after those credits expire.
In Conclusion
Every issue in this article leaves a trail in records your business already keeps, which means it can be checked now rather than discovered during an audit or a plan conversion. Ask your administrator, payroll provider, and accountant to reconcile the plan terms, the payroll settings, and the tax treatment, then put a name and a date next to each open item. Updating the next payroll run still leaves the earlier periods to resolve.
The money at stake is your own. A correction, a missed eligibility date, or a credit that lands $4,000 below the sales estimate has to be funded from somewhere, usually staff benefits, business reserves, or the contributions you planned to make for yourself. Handling those items on your timetable is generally less disruptive than responding to them under an IRS correction program, and the review is part of keeping your retirement plan competitive and cost-efficient.
WealthGen Advisors can help you assess how the plan fits your household savings, tax planning, and eventual exit, and frame the questions to resolve with your administrator and tax professional. Click the button below to schedule a meeting.
Sources
Primary sources for the numbered references in this article.
- 1IRS Notice 2024-2, Section J: Plan Amendment Deadlines and Operational Requirements.
- 2IRS Notice 2026-9: Extension of SECURE 2.0 Amendment Deadlines for IRAs, SEPs, and SIMPLE IRAs.
- 3IRS Notice 2025-67: 2026 Retirement Plan Limits and the Roth Catch-Up Wage Threshold.
- 4Treasury and IRS Final Regulations: Catch-Up Contributions, Including FICA Wage and Self-Employment Treatment.
- 5IRS: Final Roth Catch-Up Regulations and the End of the Administrative Transition Period.
- 6Treasury and IRS: Automatic Enrollment Under Section 414A, Statutory Requirements and Proposed Implementing Regulations.
- 7IRS 401(k) Plan Fix-It Guide: Traditional and Automatic-Enrollment Safe Harbor Requirements.
- 8Treasury and IRS: Long-Term, Part-Time Employee Statutory Rules and Proposed Implementing Regulations.
- 9IRS Instructions for Form 8881: Startup Credit Limits and Employer Eligibility.
- 10IRS: Retirement Plans Startup Costs Tax Credit and Employer-Contribution Credit.