Key Insights
- We can't control the interest rate.
- We can't predict the Fed's actions.
- Changing interest rates are beneficial and detrimental.
- Reallocating and diversifying assets is the best way to offset the effects.
Interest rates affect inflation
As mentioned in the opening paragraph, the Fed manipulates the interest rate as a tool to combat inflation and spark economic growth. It’s an unending cycle – interes rates are lowered and the economy begins to expand as borrowing costs decrease, making it more affordable for businesses and consumers to take on loans to grow and invest. This newfound glut of cash through cheap lending leads to a reduction in the value of the dollar, i.e. inflation. The Fed reacts by raising interest rates to get the dollar supply under control. The economy begins to flounder as corporations start posting fewer profits and it becomes expensive to take loans.Interest rates heavily influence bond prices
Interest rates have a direct and inverse relationship with bond prices. When the Fed raises interest rates, newly issued bonds will have higher rates compared to older bonds that were issued when interest rates were lower. A rise in rates can cause investors to sell older bonds for newer ones, causing the price of older ones to drop even further. Conversely, if interest rates go down, newly issued bonds will have lower rates than older bonds that were issued when interest rates were higher. If newly issued bonds offer higher interest rates, investors are less likely to buy older bonds with lower rates, which causes the price of those bonds to fall.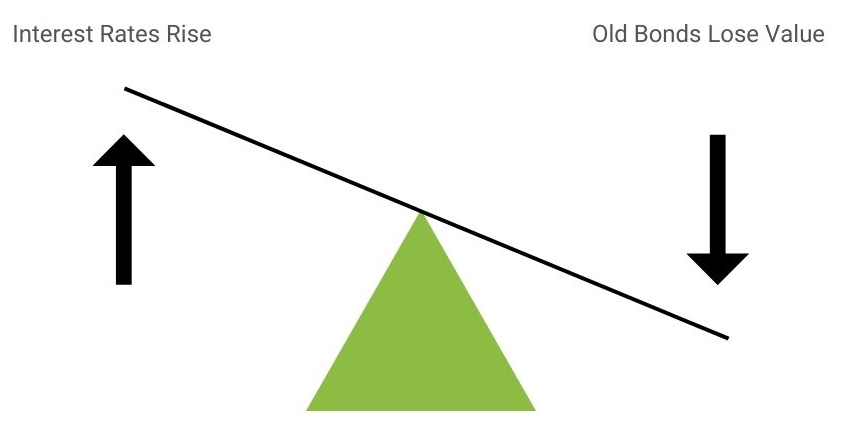 On the other hand, if newly issued bonds offer lower interest rates, investors may prefer older bonds with higher rates, which causes the price of those older bonds to rise.
So how does this affect your portfolio?
Bonds are fixed-income securities, right? Yes, you will still continue to receive your coupons from your bond at the same rate as when you purchased it (unless it is a variable-rate bond). But the market value of the bond has declined.Possible liquidity issues
If you need to sell your bond for liquidity purposes or as part of a portfolio rebalancing strategy, you may end up with a capital loss. Basically, unless you’re willing to take a loss, your options will be limited with this suddenly depreciated asset. On the other hand, if interest rates drop, your older bonds with a higher interest rate may gain in market value, allowing you to sell for a net gain.High-interest rates can reduce stock values
Interest rate changes can also impact stock prices. Many companies prefer low-interest rates because it makes money cheap, in the sense that they can cheaply borrow more money. When interest rates rise, so does their cost of borrowing money, which may reduce their profitability as a result. Additionally, when interest rates rise, investors may start selling their stock and purchasing more bonds, again potentially driving down stock prices. Some sectors, however, may benefit from higher interest rates, such as banks that earn more from the increased lending costs. Since a company’s profitability may be affected by high-interest rates, they may start paying out reduced dividends or cut them altogether. The yield offered by bonds with a now higher interest rate may be a more attractive option than a reduced dividend as well.Dividend stocks may also lose value
Since a company’s profitability may be affected by high-interest rates, they may start paying out reduced dividends or cut them altogether. The yield offered by bonds with a now higher interest rate may be a more attractive option than a reduced dividend as well.Real estate projects may lose their luster
More often than not, investors take out loans for real estate projects. Since lending costs go up with higher rates, the profitability of a project may go down. This may even be reflected across Real Estate Investment Trusts (REITs), not just direct investments. However, completed real estate projects are likely to outperform inflation in the long haul due to increasing populations and demand. For example, an apartment complex owner has complete control over the rental prices in their building. During times of high inflation, an owner can simply raise rent to make up for the loss due to inflation.Currency fluctuations
Higher interest rates may be beneficial for liquid and semi-liquid assets such as cash and money markets. Since a higher interest rate leads to a reduction in inflation (in theory), your dollar will get stronger, as in more able to purchase a larger bundle of goods and services. Money markets typically invest in short-term government bonds. Since they are short-term, it won’t be long before older bonds mature and are replaced with higher earning bonds. A strong dollar is a potentially excellent opportunity to rebalance your portfolio, as your domestic assets may begin to outweigh your international assets. To keep your asset allocation proportional to your overall risk tolerance, you can shift further purchases from domestic stocks to global stocks to get your portfolio back in line.The importance of professional advice
Of course, this may all be a lot to take in. Who has the time to stay up-to-date with how changing interest rates affects their investment portfolio? Even if one does, do they have the skills and knowledge to react in a beneficial way? Fortunately, a fiduciary financial advisor does have the time, the skills, and the knowledge to do just that. An advisor can carefully examine your risk tolerance, financial objectives, and your time horizon to create a strong portfolio capable of adapting to changing interest rates. If you’d like a free analysis of your financial plan, click the button below.Disclosures
Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment or strategy will be suitable or profitable for a client’s portfolio. All investment strategies have the potential for profit or loss. Information presented is believed to be factual and up-to-date, but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the author/presenter as of the date of publication and are subject to change and do not constitute personalized investment advice.
A professional advisor should be consulted before implementing any investment strategy. WealthGen Advisors does not represent, warranty, or imply that the services or methods of analysis employed by the Firm can or will predict future results, successfully identify market tops or bottoms, or insulate clients from losses due to market corrections or declines. Investments are subject to market risks and potential loss of principal invested, and all investment strategies likewise have the potential for profit or loss. Past performance is no guarantee of future results.
Please note: While we strive to provide accurate and helpful information, we are not Certified Public Accountants (CPAs). The information in this article is intended for informational and educational purposes only and should not be interpreted as tax advice. It is crucial to consult with a CPA, tax professional or estate attorney to discuss your personal situation.