Grant Date
Two Year Vesting Period Begins
Exercise Date
Vesting period ends and one-year holding period begins
Holding Period Ends
All conditions met – Grantee qualifies for lower Capital Gains Tax and no income tax on the bargain element.
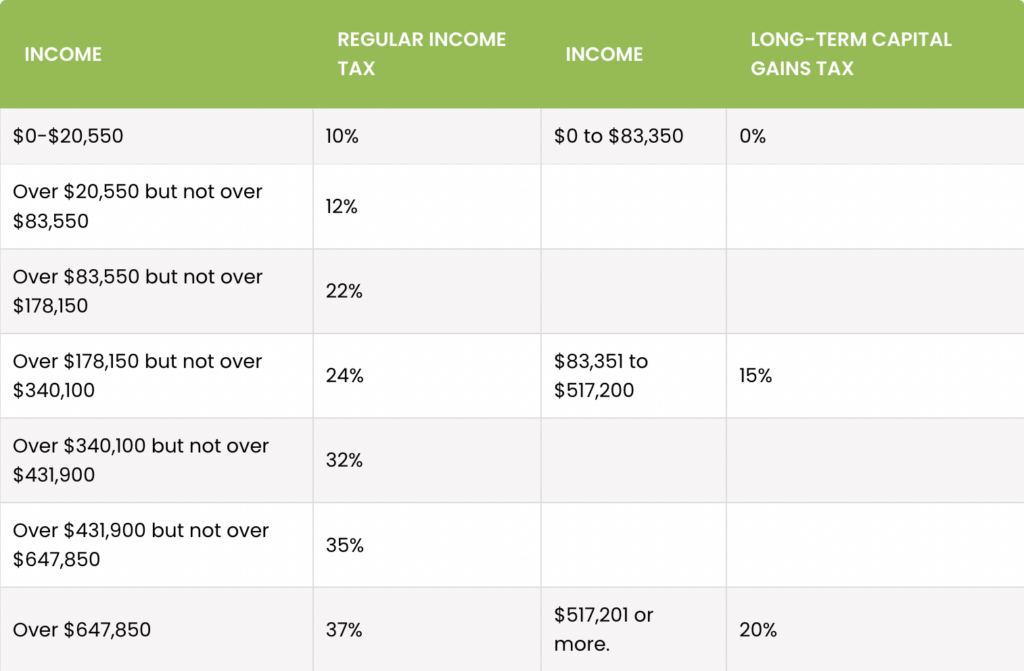
Tax Brackets
Married, Filing Jointly
|
INCOME
|
REGULAR INCOME TAX
|
INCOME
|
LONG-TERM CAPITAL GAINS TAX
|
|---|---|---|---|
|
$0-$20,550
|
10%
|
$0 to $83,350
|
0%
|
|
Over $20,550 but not over $83,550
|
12%
|
|
|
|
Over $83,550 but not over $178,150
|
22%
|
|
|
|
Over $178,150 but not over $340,100
|
24%
|
$83,351 to $517,200
|
15%
|
|
Over $340,100 but not over $431,900
|
32%
|
|
|
|
Over $431,900 but not over $647,850
|
35%
|
|
|
|
Over $647,850
|
37%
|
$517,201 or more.
|
20%
|
Scenario 1
In the worst-case scenario, James exercises early to realize the profit between the exercise price and fair market value, but then the stock price drops to zero before he manages to sell his shares. James will still pay regular income taxes on the bargain element, plus he will have lost his entire investment.Scenario 2
In a non-ideal scenario, James receives incentive stock options, and the stock price then drops and stays below the exercise price for the rest of the options’ longevity. James has spent nothing on them but also gains nothing. One can argue that he possibly lost potential profits by not simply taking a loftier salary in the first place in the hopes of attaining much more through an employee stock option plan.Scenario 3
James holds for two years to meet the two-year grant condition and exercises immediately after vesting. He sells his shares within a year, breaking the one-year hold condition. He now owes long-term capital gains tax on the difference between the sale and exercise prices and ordinary income tax on the bargain element.Scenario 4
James exercises and sells nearly straight away. He will owe regular income and short-term capital gains on the bargain element and the exercise/sell spread, respectively. Since he doesn’t receive any special tax treatment, he is said to have a Disqualifying Disposition. We’ll go into details below how this will affect his overall tax burden, as it is quite consequential and something for every ISO grantee to consider as part of their exercise strategy.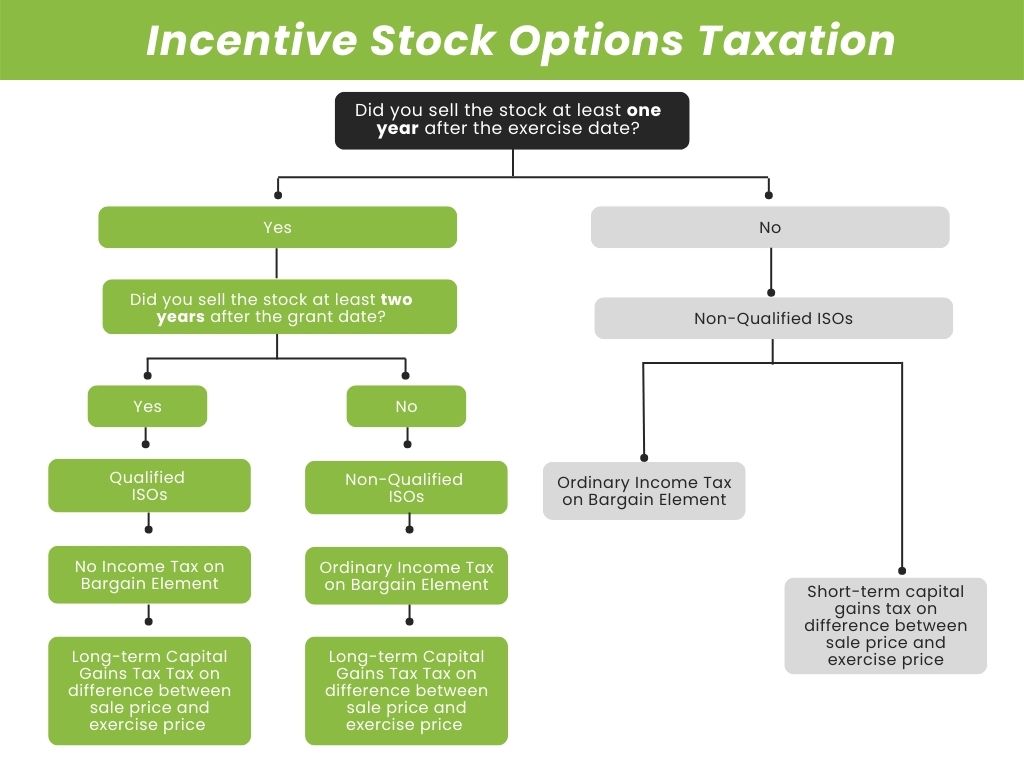 Simple, right?
Not so fast.
Because, unfortunately for you, the ISO holder, it’s not that simple. That’s because we still haven’t touched upon the Alternative Minimum Tax.Alternative Minimum Tax
The Alternative Minimum Tax (AMT) is a system of taxation implemented in 1969 to close loopholes that enabled the wealthy to pay fewer taxes. The AMT is triggered upon reaching a specific income level or receiving certain tax-advantaged income streams, or a combination thereof. Incentive Stock Options, due to their tax-advantaged nature, are one of those income streams. You may owe the IRS a much more considerable sum than expected once you calculate the AMT. Unfortunately, many grantees overlook the AMT, potentially costing them huge sums of money. Let’s imagine James earns $180,000 a year, lives in a state without an income tax, such as Florida, is married, and has 1,000 stock options with a $400 spread between the strike price and Fair Market Value when he dumps his shares. He’s fully vested, and past his holding period, so all he owes is Capital Gains tax. Unfortunately, the AMT kicks in, and, to his shock, his tax bill is $102,000!¹How to avoid the Alternative Minimum Tax
It may be possible to avoid the AMT by carefully analyzing how many options you can exercise without reaching the activation threshold. This can be quite difficult, so we highly recommend consulting with a financial advisor and CPA to evaluate the best ISO exercise strategy. Once it is calculated, you will be able to sell a certain amount of shares each year without breaking the threshold adjusted to your changing income. You can also avoid the AMT by simply exercising and selling within the same year, triggering a Disqualifying Disposition, as James did in Scenario 4. A Disqualifying Disposition disqualifies an individual from a favorable tax position. But if the favorable tax position would trigger a more expensive Alternative Minimum Tax, then it simply makes sense to pay ordinary taxes through a Disqualifying Disposition. We strongly recommend you schedule a meeting with us if you are an ISO grantee or believe you will be. They can be confusing, convoluted, and complex, so it is always best for trained professionals to comb over the details so you don’t get stuck with a huge tax bill.Further Reading
Disclosures
Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment or strategy will be suitable or profitable for a client’s portfolio. All investment strategies have the potential for profit or loss. Information presented is believed to be factual and up-to-date, but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the author/presenter as of the date of publication and are subject to change and do not constitute personalized investment advice.
A professional advisor should be consulted before implementing any investment strategy. WealthGen Advisors does not represent, warranty, or imply that the services or methods of analysis employed by the Firm can or will predict future results, successfully identify market tops or bottoms, or insulate clients from losses due to market corrections or declines. Investments are subject to market risks and potential loss of principal invested, and all investment strategies likewise have the potential for profit or loss. Past performance is no guarantee of future results.
Please note: While we strive to provide accurate and helpful information, we are not Certified Public Accountants (CPAs). The information in this article is intended for informational and educational purposes only and should not be interpreted as tax advice. It is crucial to consult with a CPA, tax professional or estate attorney to discuss your personal situation.