Tax Advantages
Non-Qualified Stock Options are less tax-advantaged than Incentive Stock Options (ISOs). Unlike ISOs that allow you to avoid paying any tax on the bargain element if exercised correctly, Non-Qualified Stock Options allow for no such avoidance. However, there are methods to lower the tax obligation on NQSOs, which we will go into below.Taxable Events
There are two taxable events applied to Non-Qualified Stock Options. How the IRS taxes them depends on the amount of time you hold the shares upon exercising your options. However, getting granted Non-Qualified Stock Options is not a taxable event in and of itself because they’re not treated as a form of income until you exercise them.Tax on the Bargain Element
For example, you receive 100 shares of XYZ options with a strike price of $5. The stock price rises to $15 a share, and you decide to exercise. You then pay income tax on that $10 spread for each option you exercised. In this particular case, you’ll be paying income tax on the $1,000 bargain element.Tax on the Sale of the Shares
The next taxable event transpires when you sell the shares you physically obtained upon exercising your options. The earnings that are taxed is calculated as the share price at the moment of sale minus the share price at exercise multiplied by the number of options exercised. The rate at which the IRS will tax them depends on how long you hold the shares after exercising. If you have held them for less than a year, they will be subject to short-term capital gains tax. If you hold them for more than a year, you will get to pay the lower long-term capital gains tax.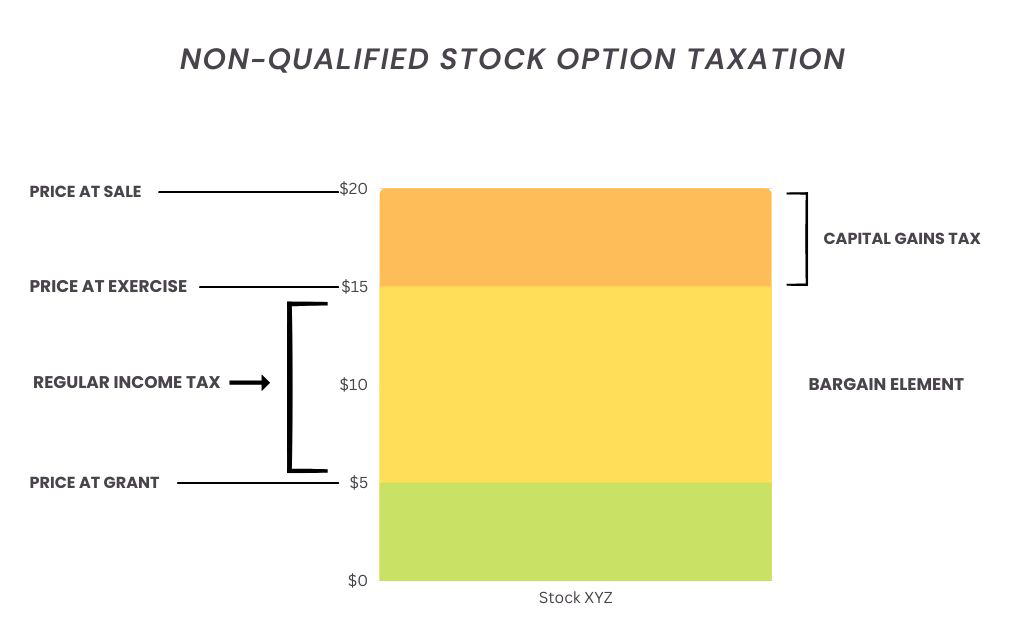
Grant Date
Grant Price of $5
Exercise Date
Stock price of $15. Income Tax is paid on the $10 difference.
Sell Date < 1 Year
Short-Term Capital Gains Tax is paid on the current Fair Market Value of $20 minus the $15 stock price at exercise.
Sell Date > 1 Year
Long-Term Capital Gains Tax is paid on the current Fair Market Value of $20 minus the $15 stock price at exercise.
Ways to Exercise Your Stock Options
Fortunately, there are a few ways to exercise your options that will help reduce risk and minimize taxes with the right combination.Sell-to-Cover Exercise Strategy
If you’d like at least to have some amount of stocks in your portfolio to get the lower tax rate, you can execute what’s known as a “sell-to-cover” strategy. In this case, you exercise and sell a set amount of options and shares that will cover the exercise and purchase another set of options and shares. The bargain element will be taxed, and then you will pay long-term capital gains tax on the shares received from the sale of the It works as follows. You have 1,000 options of XYZ stock with a $100 exercise price and a current Fair Market Value of $120. You want to buy ten shares for $1,000. You need to exercise 50 options and immediately sell them for a profit of $20 each, which gives you the $1,000 to exercise another ten options and hold the resulting shares, minus the federal income tax on that $1,000. After a year, if the stock price is still above the exercise price, you can sell those ten shares at the preferred long-term Capital Tax Rate.Cashless Exercise
If you’d rather not worry about tax rates and prefer to lock in profits, you can exercise options and sell shares simultaneously with a cashless exercise strategy. Your only profit will be the bargain element, which is taxed as regular income, as noted above. Always pay attention to what your asset allocation will look like if you decide to not sell your shares right away. Oftentimes, holding a large position in one stock goes against the principles of diversification. Some factors that may influence your decision to hold or sell include your age and time from retirement, dividends, and the belief that the company will continue being successful. What is the best strategy for you and your risk tolerance? Going over your employee stock option plan with a financial advisor will help you decide whether you should accept stock options as compensation or, if you already possess options, determine the best exercise strategies in line with your portfolio, risk tolerance, and tax situation.Disclosures
Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment or strategy will be suitable or profitable for a client’s portfolio. All investment strategies have the potential for profit or loss. Information presented is believed to be factual and up-to-date, but we do not guarantee its accuracy and it should not be regarded as a complete analysis of the subjects discussed. All expressions of opinion reflect the judgment of the author/presenter as of the date of publication and are subject to change and do not constitute personalized investment advice.
A professional advisor should be consulted before implementing any investment strategy. WealthGen Advisors does not represent, warranty, or imply that the services or methods of analysis employed by the Firm can or will predict future results, successfully identify market tops or bottoms, or insulate clients from losses due to market corrections or declines. Investments are subject to market risks and potential loss of principal invested, and all investment strategies likewise have the potential for profit or loss. Past performance is no guarantee of future results.
Please note: While we strive to provide accurate and helpful information, we are not Certified Public Accountants (CPAs). The information in this article is intended for informational and educational purposes only and should not be interpreted as tax advice. It is crucial to consult with a CPA, tax professional or estate attorney to discuss your personal situation.